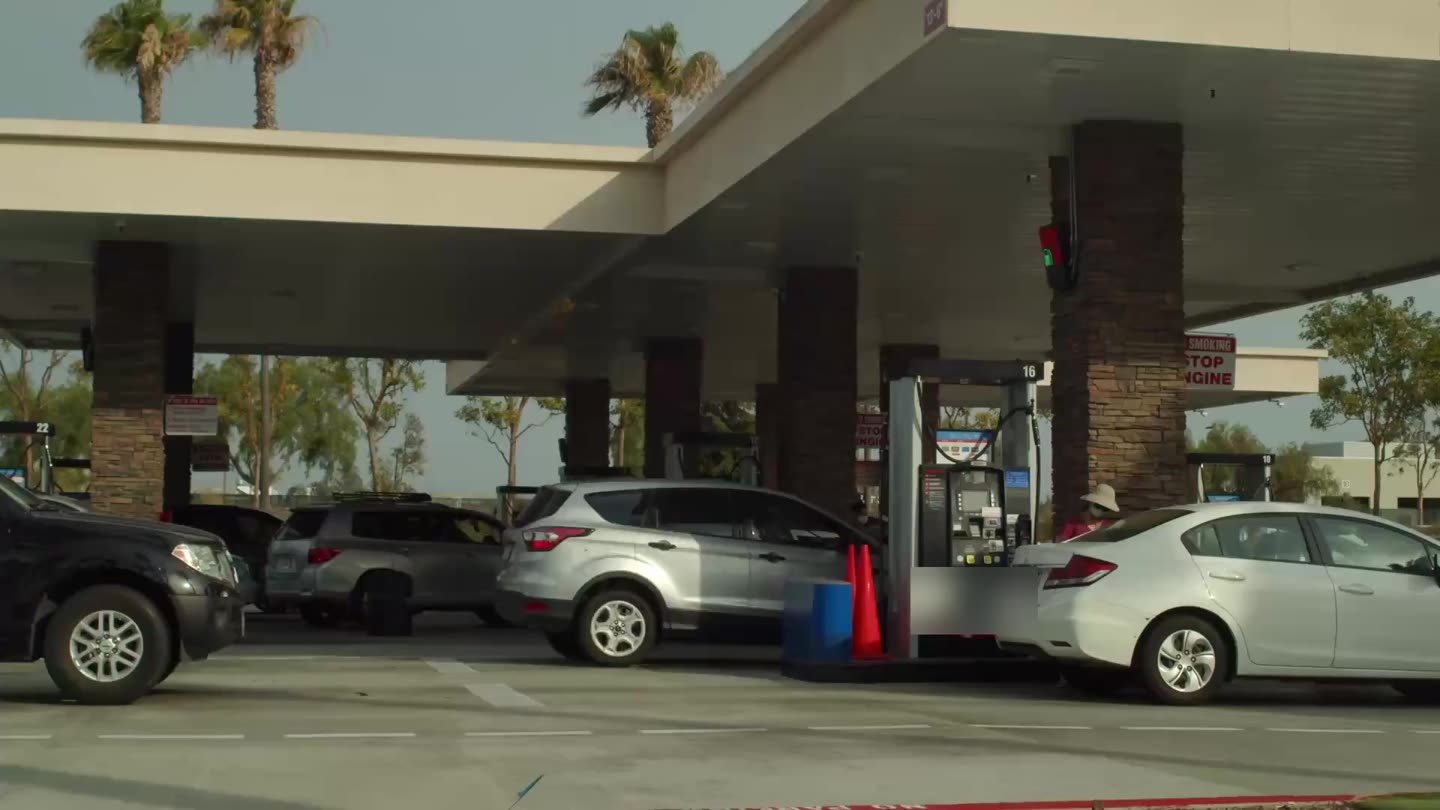
Gas stations
Fuel-and-store sites, branded or unbranded, owner-operated.
Gas station, c-store and car wash lending · Nationwide from LA
Purchase, refinance and construction financing for gas stations, convenience stores and car washes nationwide, branded or unbranded. You work directly with loan officer Shawn Rabban.

What we finance
Fuel, the store and the wash each earn differently, and lenders read them differently. Pick the property or the goal to see how the loan works.

Fuel-and-store sites, branded or unbranded, owner-operated.
Stores where inside sales carry the deal.
Washes on their own or attached to a station.
Purchase financing secured by the station real estate.
Replace a maturing note or pull cash out for upgrades.
Ground-up builds, rebuilds, canopy and tank work.
Lock up the corner before you build the station.
Terms, posted plainly
Two loans, posted plainly. The property loan is 8% with a 25-year amortization; the business loan is 8% over 10 years with no prepayment penalty. Type a loan amount on the sign to see your monthly payment. Up to $5,000,000 per borrower, both loans combined. Every loan is subject to underwriting.
Station loan terms
Up to $5,000,000 per borrower, both loans combined.
Type a dollar amount, numbers only.
Run the numbers
We fund gas stations, convenience stores and car washes across the United States. Compare the property loan and the business loan, then plan both together at our posted terms.
The sign above prices one loan. Most station buyers use both: a property loan for the real estate and a business loan for the business. Here is how they differ, using a $1,000,000 loan as the example.
| Property loan | Business loan | |
|---|---|---|
| What it finances | Property: The real estate | Business: The business itself |
| Rate | Property: 8% | Business: 8% |
| Amortization | Property: 25 years (300 payments) | Business: 10 years (120 payments) |
| Monthly payment on $1,000,000 | Property: $7,718.16 | Business: $12,132.76 |
| Total interest on $1,000,000, paid over the full amortization | Property: $1,315,448 | Business: $455,931 |
| Prepayment penalty | Property: 5% / 3% / 1% in years 1 to 3, none after | Business: None, pay it off any time |
| Personal guarantee | Property: Required | Business: Required |
| Usual share of the deal | Property: About two thirds | Business: About one third |
| Loan limit | $5,000,000 per borrower, both loans and all properties combined | |
| Property calculator | Business calculator | |
Enter the total you need. We split it about two thirds property and one third business, and you can change the split. The total can't go over $5,000,000.
See the prepayment penalty table on the property loan calculator.
Estimate only. Not a loan offer or commitment. Rate, terms and approval depend on underwriting. Business-purpose commercial loans.
How it works
A short phone interview about the property, the purpose and the numbers. You find out early whether the deal fits, before you spend time on paperwork.
Send the application and documents. Your file is reviewed against the loan programs that fit the station and your goals.
Once approved, you sign the loan documents and they go to funding. A complete file is the fastest way to the closing table.
Why stations are different
Many lenders treat a station like any other commercial property, then stall on the details. These are the four details that decide your loan.
Underground fuel tanks make every lender careful. Expect a Phase I environmental site assessment on any station loan. If it flags a concern, a Phase II may follow. In California, single-walled tanks also had to be permanently closed by December 31, 2025, so check the tank records early. A clean, current report is the single biggest thing that keeps a deal moving.
What the Phase I means for your loanA station is hard to turn into anything else, so lenders lean harder on the appraisal and on cash flow. Clean books and a realistic value matter more here than on an office or a strip center.
Branded sites come with fuel supply and franchise agreements that the lender will read. For an SBA loan, a franchised brand must appear on the SBA Franchise Directory. Unbranded stations skip that step but need strong numbers of their own.
SBA loan or private loan?Fuel gallons, store sales and car wash income earn very different margins. Lenders want each one shown on its own, backed by tax returns and financial statements, before they size the loan.
Estimate your property loan paymentGet ready
Most delays come from missing paperwork. Tick off what you have; your progress stays on this device.
Your ticks are saved on this device only. Nothing is sent to us.
Your loan officer
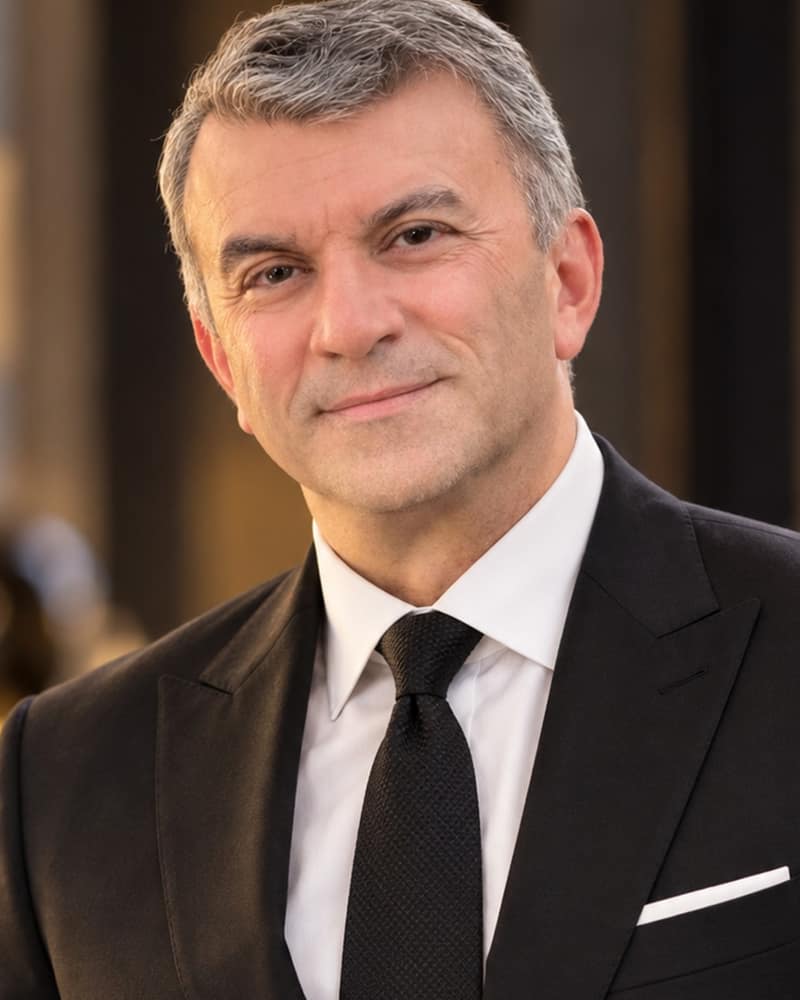
Shawn Rabban is the loan officer behind LA Gas Station Loan. You call him, you talk to him, and he stays on your deal through funding. No call center, no hand-offs.
Guides
What the report checks, when a Phase II is needed, and how lenders read the results.
Down payment, timing, franchise rules and collateral, compared side by side.
Price vs value, what gets financed, and the order to do your due diligence.
FAQ
Gas stations, convenience stores and car washes, including stations with a store or wash on the same lot. Stations can be branded or unbranded. Loans are secured by the real estate.
Yes. Plan on a Phase I environmental site assessment and an appraisal for every station loan. If the Phase I finds a recognized environmental condition, the lender may ask for a Phase II before closing. Read the Phase I guide.
Yes. Branded and unbranded stations both qualify. For a branded site, have your franchise or fuel supply agreement ready, because the lender reviews it as part of the file.
Yes. Both established operators and start-ups can apply. First-time owners should include a business plan and a resume that shows any station, retail or management experience.
Three years of personal and business tax returns, personal and business financial statements, proof of your down payment, and the lease or franchise agreement if there is one. Use the checklist above to track it.
Two loans. The property loan (real estate) is 8% with a 25-year amortization, a personal guarantee, and a prepayment penalty of 5% in year 1, 3% in year 2 and 1% in year 3, with none after. The business loan is 8% with a 10-year amortization, a personal guarantee and no prepayment penalty. Together they can total up to $5,000,000 per borrower. See your payment.
Yes. We are based in Los Angeles and fund gas stations, convenience stores and car washes nationwide.
Speed depends on the file. We can close as soon as all the information is in, so a complete document package is the fastest path. Call Shawn to talk through the timeline for your deal.
Call Shawn with the address, the price or value, and what you want to do. You will know what to expect from the very first conversation.